Request a demo
Please fill out this form to request a demo.
Loading form
Blog
Finn Doherty, Associate Consultant
In Q3, CleanTrade hosted the first-ever exchange-executed clean energy VPPAs, with two transactions closing during a quarter of policy shocks and record demand. That pace was possible because of the price transparency, standardized terms, and compliance confidence of a CFTC-registered marketplace.
Our Q3 2026 State of the Market for Clean Power Offtake report analyzes what moved the offtake market this quarter, and what it means for buyers and sellers. Here’s a preview.
Two policy developments reshaped the market in Q3, and CleanTrade activity showed their impact as it happened.
The first was the July 4, 2026 deadline to begin construction for federal tax credit eligibility. Projects that missed it must now reach commercial operation by December 31, 2027 to qualify. For many greenfield projects, that timeline is a stretch, so developers instead need to recover more of their costs through offtake pricing.
CleanTrade offers reflected this almost immediately. In ERCOT, MISO, and PJM, the median greenfield solar offer price for listings posted after July 4 rose 8-15%, compared with listings posted before the deadline. Developers on the platform continually reprice to match current conditions, so these are real, transactable offers. This shift was visible in our Offtake Activity Monitor monthly updates.
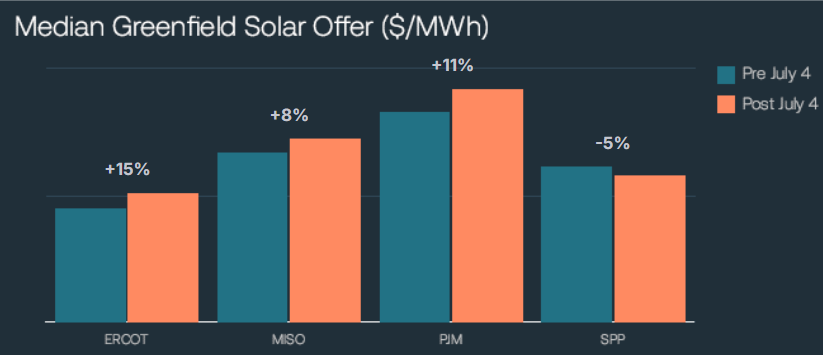
Median greenfield solar offers, pre- and post-July 4th deadline.
Source: Resurety State of the Clean Energy Offtake Market, Q3 report
The second policy development came on August 6, when a judicial injunction ordered the Pentagon to resume reviewing pending wind project applications. That could unblock more than 100 projects totaling 30 GW. A new greenfield wind offer was listed on CleanTrade the next day, and buyer and seller activity increased over the following weeks.
ERCOT and PJM faced very different supply and demand conditions in Q3. In both markets, though, offtake pricing was driven by expectations of future load growth.
In late July, ERCOT set a record peak demand of 91.1 GW, roughly 6% above the previous high. Prices stayed relatively stable compared with past peaks, largely because renewables and storage met the load. Solar alone served 32% of demand during the peak. That stability held through August, a month historically marked by cooling-driven price spikes. Even so, ERCOT solar bids and offers on CleanTrade held flat or edged up slightly. Participants were pricing in future data center demand, despite Governor Abbott’s pause on new data center development.
PJM, the other leading market for data center growth, faces the opposite problem: a capacity shortfall. It again fell short of its capacity target in its most recent auction, and as supply tightens, each demand spike brings more volatile pricing. Bid and offer prices for operating solar in PJM each rose by 10% as power market forwards adjusted to tighter supply.
For a deep dive into how these issues and more affected bids and offers in each ISO, the full Q3 report is available exclusively to CleanSight Reports subscribers. Contact [email protected] to gain access.
Complete this form for access to CleanSight Reports.

 Loading form